What is the scope and significance of the Product Implementation Services Market?
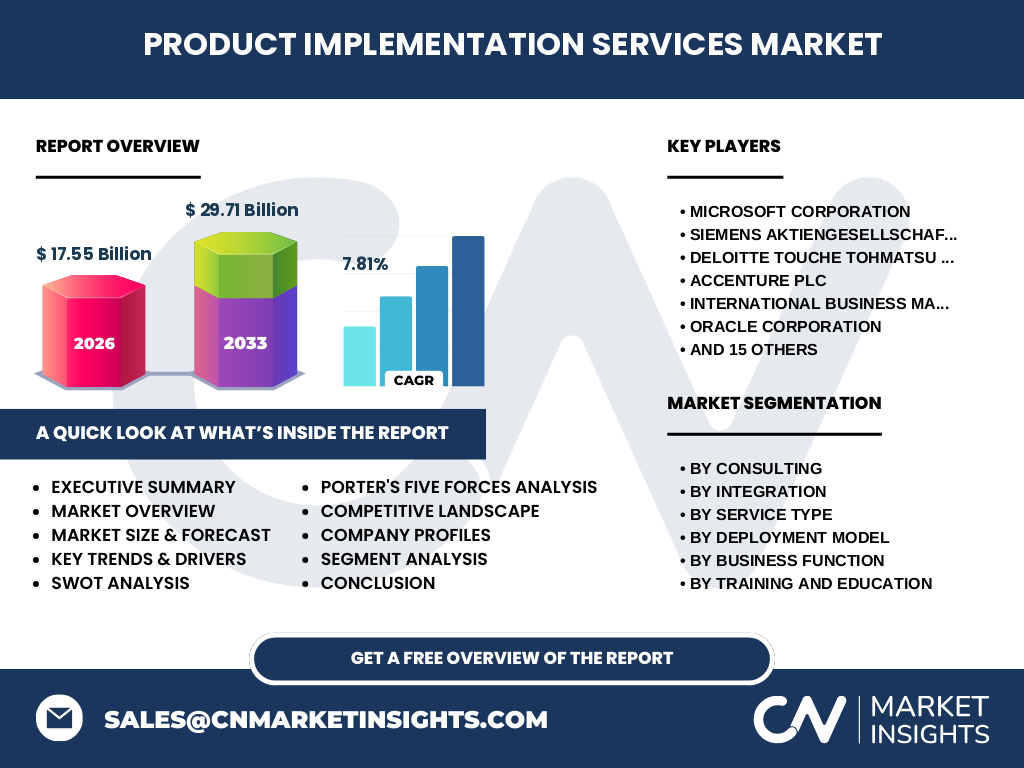
The Product Implementation Services Market serves as the critical backbone for digital transformation, encompassing everything from initial planning to full-scale system integration. Valued at 17.55 Billion in 2026, this market is essential for ensuring that complex software deployments align with organizational workflows, compliance mandates, and operational efficiency requirements across global enterprise environments.
Structural Growth Drivers and Market Constraints
Growth is propelled by accelerated cloud adoption and the necessity for process alignment in legacy-heavy industries. Conversely, the market faces significant logistical hurdles, including localized regulatory constraints such as GDPR compliance and the scarcity of specialized technical talent. Companies must navigate these headwinds to capitalize on the increasing demand for seamless Data Migration Services.
Emerging trends and long-term growth patterns
We observe a paradigm shift toward Hybrid Implementation models, allowing firms to bridge on-premise stability with cloud agility. Knowledge Transfer Workshops are becoming increasingly vital as organizations seek to reduce post-deployment dependency. These trends suggest that long-term value is shifting from simple software installation toward Performance Optimization Services that deliver continuous ROI.
How did COVID-19 redefine the trajectory of implementation services?
The pandemic acted as a forced catalyst, shifting the market toward remote-first Cloud-Based Implementation. While initial project timelines stalled, the recovery phase saw a surge in demand for Application Integration Services to support distributed workforces. Industry players like Microsoft and Accenture pivoted rapidly, setting a new standard for agile delivery that persists today.
Competitive Benchmarking and Market Concentration
The landscape is highly fragmented yet competitive, featuring global giants like IBM, Oracle, and Infosys alongside niche specialists like Surety Systems. Concentration is highest in System Integration Services, where large-scale Tier-1 vendors leverage deep industry expertise to secure high-value contracts, while smaller firms often dominate specialized Change Management Consulting verticals.
Executive Summary: Key Findings of the Market Outlook
The Product Implementation Services Market is poised for a significant expansion, reaching 29.71 Billion by 2033 at a CAGR of 7.81%. Our analysis reveals that Consulting and Integration segments will lead growth as businesses prioritize Technology Readiness to maintain competitive advantages in increasingly digital-first industrial landscapes.
Market Forecast 2027 to 2033
Projected growth estimates suggest a robust trajectory, with market valuation set to rise from current levels to 29.71 Billion by 2033. This sustained momentum is underpinned by a 7.81% CAGR, driven by persistent demand for Post Implementation Support and the continuous need to optimize legacy Finance and Accounting software systems.
Segmentation Analysis: Core Components and Market Roles
The market is segmented by Consulting, Integration, Support, and Training. System Integration Services represent the largest share, facilitating interoperability across disparate platforms. Meanwhile, Change Management Consulting plays a vital role in ensuring organizational adoption, particularly in highly regulated sectors like Banking and Finance where process accuracy is strictly enforced.
Regional Market Performance and Geographic Distribution
North America and Europe currently hold the largest market share due to mature IT infrastructures, while the Asia-Pacific region is emerging as the fastest-growing hub. Localized constraints, such as port logistics in the manufacturing sector and varied data sovereignty laws, dictate regional delivery models, favoring local service providers like NTT DATA and Tata Consultancy Services.
In-depth regional review of key markets
Our research indicates that the European market is heavily focused on compliance-driven implementation, especially within the Healthcare and Telecommunications sectors. Meanwhile, in North America, the focus is squarely on scalability and Cloud-Based Implementation. Each region demands unique Documentation and Learning Services to bridge the gap between global platforms and localized operational requirements.
Company Profiles and Strategic Positioning
Strategic leaders like Siemens emphasize Industrial IoT integration, while Deloitte and Ernst & Young focus on Process Alignment Consulting. Capgemini and Cognizant differentiate through strong vertical domain knowledge, allowing them to lead complex Data Migration projects that require deep insight into specific industry raw materials and supply chain complexities.
Porter's Five Forces Analysis
The market faces moderate-to-high competitive rivalry among established players. While the threat of new entrants is mitigated by the need for massive human capital, the bargaining power of buyers is rising, forcing vendors like Wipro and HCL to focus on outcome-based pricing models and superior Issue Resolution Services to maintain market share.
SWOT Analysis of the Industry
Strengths include robust demand for digitalization; Weaknesses involve high service costs and project complexity. Opportunities lie in emerging AI-driven performance optimization, while Threats remain centered on data privacy breaches and potential economic volatility affecting R&D budgets. Companies like Atos are currently hedging these risks by diversifying their Support and Maintenance offerings.
Value Chain Analysis
Value flows from raw technical components to high-level strategic consulting. The chain begins with Technology Readiness Consulting, moves through System Integration and Data Migration, and concludes with long-term Post Implementation Support. This structure ensures that vendors remain deeply embedded in the client's business lifecycle, securing long-term service revenue.
Strategic Investment Insights and High-Potential Areas
Investors should monitor firms specializing in Hybrid Implementation and Automated Support Services. Our research identifies the intersection of Operations Management software and Industrial Manufacturing as a primary growth vector. Companies capable of delivering scalable End User Training Programs are particularly well-positioned to command premium margins as enterprise software complexity continues to outpace internal adoption capabilities.
Conclusion and Key Takeaways
The Product Implementation Services Market is a high-growth sector with a clear trajectory toward 2033. Success will belong to organizations that can master integration complexity, navigate regional regulatory nuances, and provide consistent, high-value Issue Resolution Services. With a projected value of 29.71 Billion, the market remains a cornerstone of the global digital economy.
Research Methodology: How are estimates triangulated?
Our baseline estimates are derived from triangulation: cross-referencing global trade registry data, conducting primary stakeholder interviews with CTOs and project managers, and analyzing macroeconomic indicators from bodies like the IMF. This multi-layered approach ensures that our 7.81% CAGR forecast reflects both realized project spending and anticipated market expansion trends.
Scope and Parameters of the Report
This report covers the Product Implementation Services Market across seven core business functions, including Sales, HR, and R&D. It spans global regions and accounts for all deployment models from on-premise to hybrid. Limitations include the exclusion of pure software development services that lack an implementation or integration component.
Recent Developments and Market Movements
Recent strategic moves include IBM's increased focus on AI-augmented Data Migration and Infosys's aggressive expansion in Healthcare implementation. These developments signal an industry-wide pivot toward automation-first delivery models. EffectiveSoft and N-iX are also making waves, securing niche partnerships that enhance their capability to serve specialized manufacturing and logistics segments globally.